
Walmart MoneyCard®
- Rating
- 3.8
- Downloads
- 500.00K
- Content Rating
- Mature 17+
Walmart MoneyCard® - Screenshots
Pros
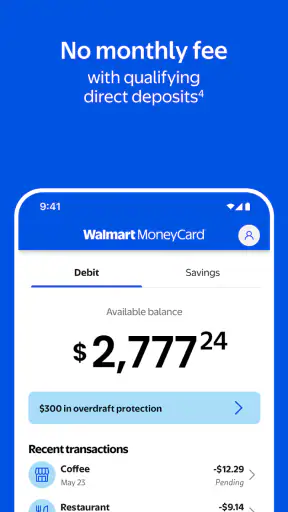
- No monthly fee when you receive qualifying direct deposits.
- Mobile check deposit lets you add funds without visiting a store.
- Early direct deposit may provide access to eligible paychecks sooner.
- FDIC insurance helps protect eligible balances when program conditions apply.
- Card controls and transaction alerts can help monitor spending.
Cons
- Cash reload fees may apply at participating retailers.
- Some features require identity verification and approval.
- Out-of-network ATM withdrawals can incur additional fees.
- Not all deposits qualify for early access or fee waivers.
- Account access depends on the app
- card
- and a reliable internet connection.
Walmart MoneyCard® - Description
- App Name
- Walmart MoneyCard®
- Package Name
- com.greendotcorp.walmart
- Developer
- Green Dot
- Category
- Finance
- Last Updated
- Mar 12, 2025
- Version
- 2.7.0
I approached Walmart MoneyCard® as a practical finance app rather than something designed to replace every banking tool. Its purpose is easy to understand: give MoneyCard users a mobile place to keep an eye on their account and handle everyday money tasks. After spending time with it, I found that its value depends less on flashy extras and more on whether it fits the way you already manage spending, deposits, and card activity.
The app comes from Green Dot and is free to install, which makes trying it relatively low-risk for someone who already uses the Walmart MoneyCard service. It belongs firmly in the personal finance category, and its mature age classification is worth noticing before a teenager or family member downloads it. The current release is version 2.7.0, and it supports devices running Android 9 or later.
My overall impression is that the app is most useful as a daily control panel. I would not choose it simply because it is associated with Walmart; I would choose it if I wanted a straightforward way to check the balance and manage a MoneyCard account from a phone. That distinction matters, because a prepaid card companion is not automatically the best fit for someone seeking a full bank relationship, advanced budgeting, or investment tools.
How the app feels during ordinary money tasks
Speed expectations when checking an account
The first thing I look for in a finance app is how quickly it gets me to the information I need. With this one, the useful standard is not entertainment-app speed. It is whether I can open the app, orient myself, and confirm my available money without feeling that the process is getting in the way. For a quick balance check before buying groceries, that simple path matters more than a crowded dashboard.
I also prefer finance apps that make the next action obvious. A cardholder may open the app for one reason and then notice a recent transaction or decide to move money into a more useful spending plan. The interface needs to support that change of intention without turning a two-minute check into a long session. Walmart MoneyCard® works best when I treat it as a focused utility: open it for a specific account question, complete the task, and close it.
That focus can be a strength for people who dislike complicated banking interfaces. It is also a limitation if you expect the depth of a traditional bank application. A conventional bank may bring checking, savings, credit products, bill pay, transfers, and detailed financial tools into one place. This app is better understood through the MoneyCard itself, so its usefulness is naturally narrower.
A realistic everyday scenario
Imagine I am leaving work and need to decide whether I can afford groceries, a prescription, and a small household purchase. I open the app before reaching the checkout, review the account, and compare the planned spending with what is available. That is a modest use case, but it is exactly where a mobile card companion can prevent an avoidable surprise.
The same routine can help when I am tracking a card used for a specific purpose. For example, I might use the MoneyCard for weekly spending and check it before making a larger purchase. The important habit is to check before committing, not after. An app can make that habit convenient, but it cannot replace my judgment about upcoming expenses or money that has not yet arrived.
One useful technique is to separate “checking” from “investigating.” I would use the app for a fast balance glance during the day, then review recent activity later when I have time to confirm that each transaction makes sense. That reduces the temptation to make rushed decisions from a single number. It also gives me a clearer way to notice an unfamiliar charge and begin dealing with it promptly.
What happens during heavier use
Finance apps are often used in bursts rather than for long continuous sessions. A busy moment might involve checking the balance, looking at activity, returning to the account view, and repeating the process after a purchase or deposit. Another demanding situation is preparing for travel, when I may want to check spending several times and make sure the card remains usable.
In those moments, the app’s practical performance depends on more than the opening screen. Navigation should remain understandable when I move between account details and transaction information. I would rather have a restrained layout that keeps me oriented than a visually ambitious design that hides important money details behind decorative panels.
There is a trade-off here. A focused prepaid-card app can feel less overwhelming than a full banking suite, but it may also leave me wanting more context. If I need long-term category analysis, detailed cash-flow planning, or a broad view of several financial accounts, I would probably use a separate budgeting tool or a bank app alongside it. This is not a failure; it is a reminder to judge the app by the job it is meant to do.
For repeated checks, I would avoid refreshing obsessively. A transaction or account change can involve more than the app’s own screen, so repeatedly reopening the same view does not necessarily produce a better answer. My better workflow is to check once, wait for the relevant activity to settle, and then review the account again when I have a concrete reason.
Reliability and what to do when something feels wrong
Reliability matters more in finance than in most app categories. If a social app pauses, I can try again later. If a money app appears stuck while I am making a purchase decision, uncertainty is much more uncomfortable. I therefore judge Walmart MoneyCard less by whether every session feels instant and more by whether I can recover calmly when the app does not immediately show what I expect.
My first recovery step would be to check whether the problem is limited to the screen I am viewing. I would return to the main account area, avoid submitting the same action repeatedly, and give the app a moment before trying again. Duplicate attempts are a poor habit in any financial workflow because they can create confusion about what actually went through.
If the app closes or behaves unexpectedly, I would reopen it and verify the account state before taking another action. I would also keep the physical card and any relevant account support route available for situations where the phone is not the right place to resolve an urgent issue. A mobile app is convenient, but it should not be the only part of my plan when access to money is time-sensitive.
That recovery mindset is especially important for people who interpret a temporary display problem as proof that a transaction failed. I would not make that assumption. I would look for a confirmed account change or transaction record before repeating anything. This is a small but meaningful distinction between using a finance app casually and using it responsibly.
Device constraints and the practical cost of installation
The Android requirement is clear enough for most modern phones, but owners of older devices should check compatibility before planning around the app. Support for Android 9 and newer keeps the app available to a broad range of devices, although an older phone may still offer a less comfortable experience if storage is tight, the operating system is outdated, or other apps compete heavily for resources.
I would not expect a finance companion to be a major drain compared with games, video editors, or constantly active social apps. Still, the phone itself can affect how dependable any account tool feels. A nearly full device, an unstable connection, or aggressive background restrictions can make loading and sign-in more frustrating even when the app is functioning normally.
For that reason, I would install it on the phone I actually carry, not on an old spare device that is rarely connected or maintained. I would keep the operating system current when possible, leave enough storage for normal updates, and avoid testing an important account workflow for the first time while standing in a checkout line. A few minutes of preparation can prevent a stressful first use.
Privacy and security habits also belong in the device discussion. I would use a screen lock, avoid signing in on a shared phone, and be careful with notifications that might reveal financial details to someone looking at the lock screen. These are not special features of this app; they are sensible precautions whenever a phone provides access to money.
Who will benefit most from it
I see the strongest fit for an existing Walmart MoneyCard user who wants mobile access to everyday account information. It can be useful for someone who prefers prepaid spending boundaries, wants to monitor activity without carrying paperwork, or needs a convenient way to check the account before purchases. It also suits people who value a direct, task-oriented finance experience over a large collection of banking tools.
It may be particularly helpful for a person who is trying to make spending more deliberate. Checking the account before a purchase creates a pause between wanting something and paying for it. That pause is not a budgeting system, but it can support one. I would pair the app with a simple weekly note listing fixed bills and upcoming expenses, then use the account view to confirm what is available for flexible spending.
I would be more cautious about recommending it to someone who has not decided whether a MoneyCard account fits their financial life. Installing the companion app does not, by itself, solve questions about fees, funding methods, customer support, cash access, or whether a prepaid arrangement is preferable to a bank account. Those decisions should come first. The app is a management tool, not a substitute for understanding the underlying service.
I would also steer advanced users toward a broader banking or budgeting setup if they need consolidated accounts, detailed reports, or sophisticated planning. Someone who wants to connect several financial institutions and examine spending trends may find a dedicated budgeting service more suitable. In that case, this app can still serve its narrow purpose, but it should not be expected to become the center of the entire financial system.
How it compares with usual alternatives
Compared with a traditional bank app, Walmart MoneyCard is more specialized. A bank application usually makes sense when I want a wider range of account products and a more complete financial relationship. The MoneyCard app makes more sense when the card itself is the center of my daily spending and I want a companion built around that account.
Compared with a general budgeting app, it is closer to the source of the spending activity than to an analysis layer. A budgeting app may help me plan categories and compare several accounts, while this app is more appropriate for checking the MoneyCard account directly. I would not expect one to replace the other for every user; they solve different problems.
Compared with managing a card through a mobile website, a dedicated app can be more convenient for repeated checks because it is already part of the phone routine. The advantage is strongest when I need quick access during ordinary errands. The website approach may still be preferable for someone who rarely checks the account or does not want another finance app installed.
The app’s rating sits at about 3.8 from roughly 3,700 ratings, with close to 1,900 written reviews and more than 500,000 installs. Those figures suggest an established user base without making the app a universal recommendation. I read that combination as a reason to consider personal fit carefully: enough adoption to make it a serious option, but not a reason to ignore individual experiences with access, support, or workflow.
Small habits that make the experience better
My first tip is to decide what question I am asking before opening the app. “Can I spend this amount today?” is more useful than aimlessly browsing. A clear question makes the session shorter and reduces the chance that I will confuse a balance check with a complete picture of my finances.
My second tip is to review activity at a quiet time rather than only during a purchase. That is when I can identify recurring spending, notice anything unfamiliar, and compare the account with my own notes. The app becomes more valuable when it supports a routine instead of being used only after something goes wrong.
My third tip is to treat displayed information as a decision aid, not permission to spend every available cent. I would leave room for pending obligations and planned expenses. This is especially important with a prepaid spending approach, where the visible amount can feel reassuring even though part of it may already have a purpose.
Finally, I would keep a backup recovery plan. I would know how to contact the relevant support channel, keep my device accessible, and avoid making repeated actions when the app appears slow. That preparation is not glamorous, but it is one of the most valuable ways to reduce friction in a finance app.
My performance verdict
Walmart MoneyCard® earns my recommendation for a specific audience: people who already use the Walmart MoneyCard and want a focused mobile way to monitor and manage that account. Its free availability, recognizable developer, and straightforward role make it easy to consider. The app is not trying to be a complete financial command center, and I think it is better judged honestly as a card companion.
My verdict is more reserved for users seeking advanced budgeting, multiple-account management, or a traditional bank replacement. In those cases, another finance app may be a better primary tool, with this one used only when MoneyCard access is needed. I also would not rely on any finance app without sensible phone security and a recovery plan for moments when the device or connection is inconvenient.
For everyday checks, planned spending, and keeping a closer eye on card activity, the app has a useful place. Its strongest quality is focus: it can help turn account awareness into a regular habit without demanding a complicated financial system. If your financial life already revolves around the Walmart MoneyCard, this is a practical companion; if it does not, the app alone is not a reason to change how you bank.
FAQ
What is Walmart MoneyCard® and how does it work?
Walmart MoneyCard® is a reloadable prepaid debit card and mobile banking app designed for everyday spending and money management. After opening an account and receiving approval, users can add money through eligible methods, check their balance, deposit checks where available, pay bills, transfer funds, and use the card wherever its network is accepted. It is not a traditional bank account, and features may depend on eligibility, location, and account verification.
How can I add money to my Walmart MoneyCard® account?
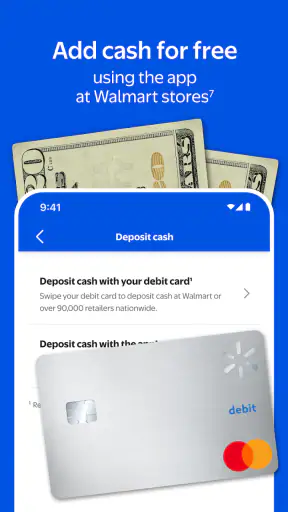
The app offers several ways to fund a Walmart MoneyCard® account, including direct deposit, cash reloads at participating Walmart locations, bank transfers, and other supported deposit options. Availability, processing times, and fees can vary depending on the method used. Before adding money, review the current terms in the app because reload limits, identity verification requirements, and service charges may apply to certain transactions.
Are there fees for using Walmart MoneyCard®?
Walmart MoneyCard® may include fees for some services, such as monthly maintenance, cash reloads, ATM withdrawals, expedited card delivery, or specific transfers. The exact cost can depend on the account plan, qualifying deposits, transaction type, and current promotional terms. Users should carefully check the fee schedule shown during enrollment and inside the app rather than assuming every feature is free.
Can I use Walmart MoneyCard® for direct deposit, bill payments, and ATM withdrawals?
Yes, eligible users can generally use Walmart MoneyCard® for direct deposit, recurring payments, everyday purchases, and ATM withdrawals, subject to account limits and network availability. The app helps users monitor transactions and manage bills, while the physical card can be used at participating merchants. ATM operators may charge additional fees, and some transactions may require verification or have daily limits.
Is Walmart MoneyCard® safe, and what should I do if my card is lost?
Walmart MoneyCard® includes account security features such as login protection, transaction alerts, card controls, and the ability to lock a card through the app, although the exact tools may vary by device and account status. If your card is lost, stolen, or used without permission, lock it immediately, contact customer support, and review recent activity. Never share your password, PIN, or verification codes.


